Behind the Data – Changing Payment Patterns in Ireland: National and County-level Trends
Patrik Gorše*
September 2026
Irish households are paying in new ways: the number of cash withdrawals is declining, online spending is approaching the same levels as spending in-stores, and at point-of-sale terminals mobile wallets have overtaken physical contactless cards in both volume and value. This article measures the extent of each change since late 2022, compares Ireland to the euro area, and finds Irish counties moving at similar speeds on mobile wallet adoption, but having different trends in the value of cash withdrawals.
Understanding how households choose to pay has become increasingly important as Ireland’s payment landscape changes. Digital payments offer convenience and new ways to pay, while traditional payment methods remain vital for a significant portion of population. Public policy aims to keep both available.
Ensuring cash remains accessible is a key objective of Ireland’s National Payment Strategy (NPS) which delivered the Access to Cash legislation, under which the Minister for Finance seeks to ensure that access to cash remains sufficient and effective across the country. In addition, the NPS aims to ensure that all sectors of the economy are aware of their obligations with regards to the acceptance of cash under the forthcoming EU Regulation on the legal tender of banknotes and coin.
Earlier Behind the Data articles examined how card spending changed during the COVID-19 pandemic and how that varied across sectors. More recently, the introduction of enhanced card spending data provided first insights into the growing use of contactless and mobile wallet payments. Two new Central Bank Signed Articles provide complementary perspectives on Ireland’s evolving payment landscape: How Ireland Pays: Mapping the Payment Ecosystem (PDF 1.21MB) examines the structure and participants in retail payments, while The Economics of the Evolving Payments System: Implications for Policymaking (PDF 1.54MB) investigates the economic impacts and policy challenges of payment innovation. Such analyses are relevant to the Central Bank of Ireland’s study on the Cost, Usage and Efficiency of Retail Payments and its Research Agenda on digitalisation.
This Behind the Data builds on the previous work by the Central Bank of Ireland and asks whether changes in Irish card payment and cash withdrawals represent a common trend or whether they differ across payment channels and counties. This is done by combining the Central Bank of Ireland’s monthly card payment statistics with the European Central Bank’s payment survey and county-level data from the Central Statistics Office (CSO). These sources enable the comparison of national trends with the euro area and analysis of differences across Irish counties.
The Data
The data come from the Central Bank's Monthly Card Payment Statistics, which begin in October 2022. Card providers based in Ireland, including the Irish branches of foreign banks, report each month on the number of personal credit and debit cards issued to households living in Ireland and the value and volume of card payments. This article uses domestic spending up to June 2026. The county analysis combines these statistics with the CSO's Census 2022.The county-level comparisons use the county where a payment is recorded, not where the cardholder lives.
Card payment statistics split spending three ways. First, where a payment happens: online or in-store. Second, how in-store payments were made: card and PIN, a contactless card payment, or a contactless payment with a mobile wallet – mostly Apple Pay and Google Pay – which is counted inside the contactless total. Third, the county where a payment is recorded. Additionally, the dataset records card-based cash withdrawals, which combine ATM withdrawals and cashbacks. For each payment instrument both value (euros) and volume (number of transactions) are collected.
Our data record only card-based transactions. We do not see credit transfers between accounts, direct debits, or cash payments themselves. While we observe a fall in cash withdrawals, specifically from ATMs and cashbacks (over the counter cash withdrawals at banks, post offices, retail outlets and similar services are not included), it is important to note that cash withdrawals do not equal the level of cash spending. Once withdrawn, cash can remain in circulation for some time and be used for multiple transactions or can be retained as a store of wealth for a prolonged period. While the data cannot be definitive on the use of cash as a payment method, it is likely that part of the declining value of card-based cash withdrawals, when considered alongside the value of card payments increasing, is accounted for by declining use of cash as a payment method.
The ECB’s study on the payment attitudes of consumers in the euro area (SPACE survey), carried out between September 2023 and June 2024, is used throughout to compare the Irish card data with consumer reported behaviour across the euro area.
People take out cash less often, but still value it as a payment method
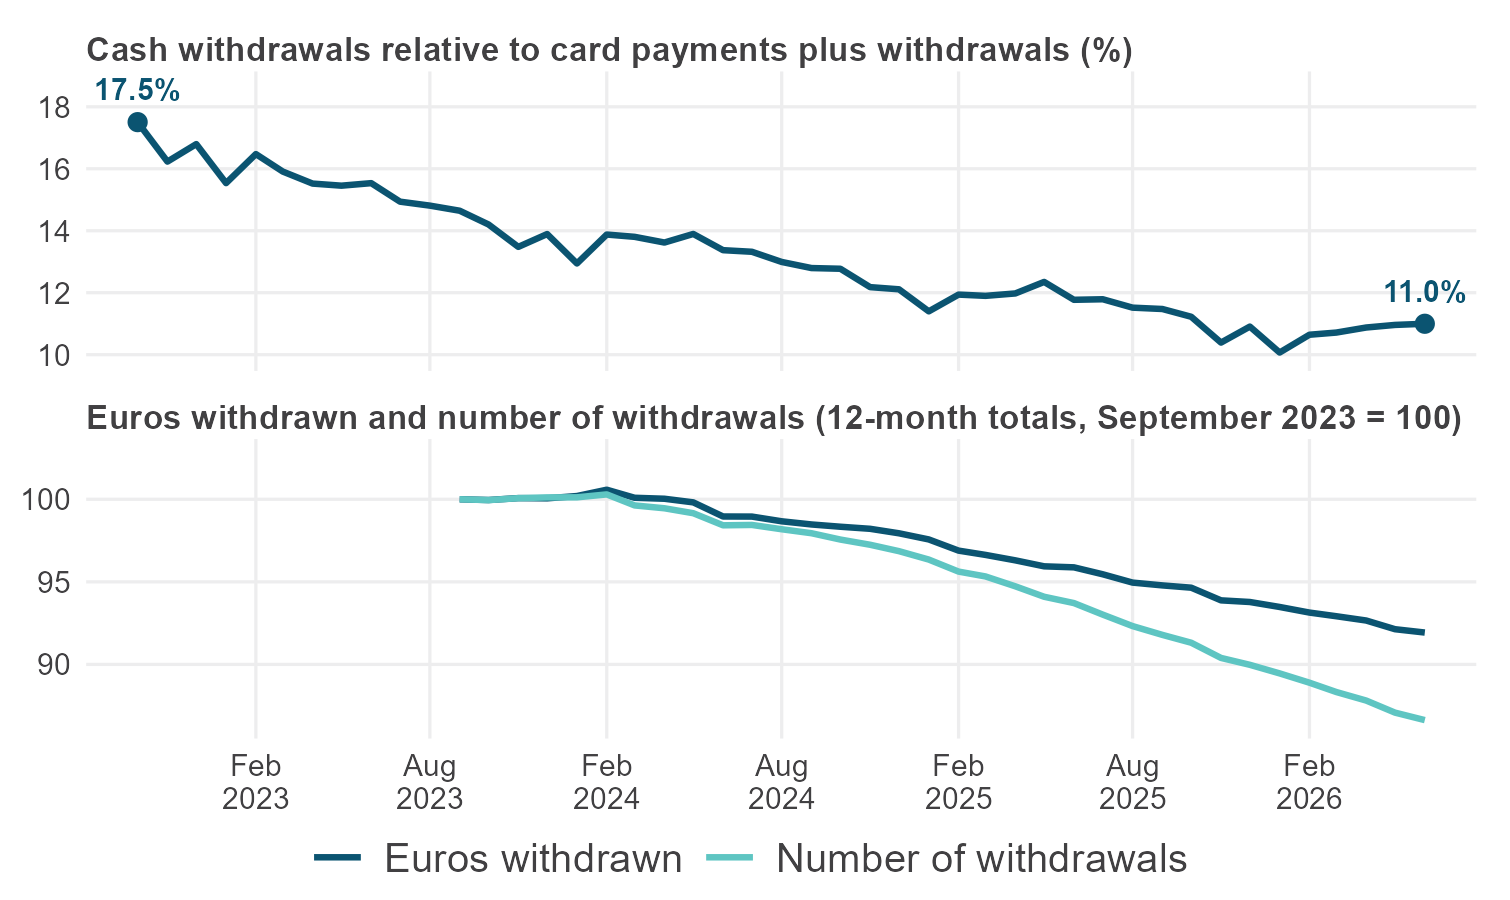
Cash withdrawals have decreased relative to card payments. In October 2022, the value of cash withdrawals was 17.5% of combined card expenditures and cash withdrawals. By June 2026, they were 11.0%, a fall of six and a half percentage points in under four years (Chat 1).
Focusing exclusively on the volume of cash withdrawals, in the past two years the number fell by 12%, from 89.9 million a year to 79.1 million, while the amount taken out fell by only 7%. People are withdrawing cash less often, averaging 1.28 withdrawals a month per resident, down from 1.45.
Chart 1: Cash withdrawals have fallen relative to card payments, and fewer withdrawals are being made
Source: Central Bank of Ireland, Monthly Card Payment Statistics.
Notes: Cash withdrawals include ATM withdrawals and cashback. The top panel divides them by card spending plus cash withdrawals. The bottom panel uses 12-month averages.
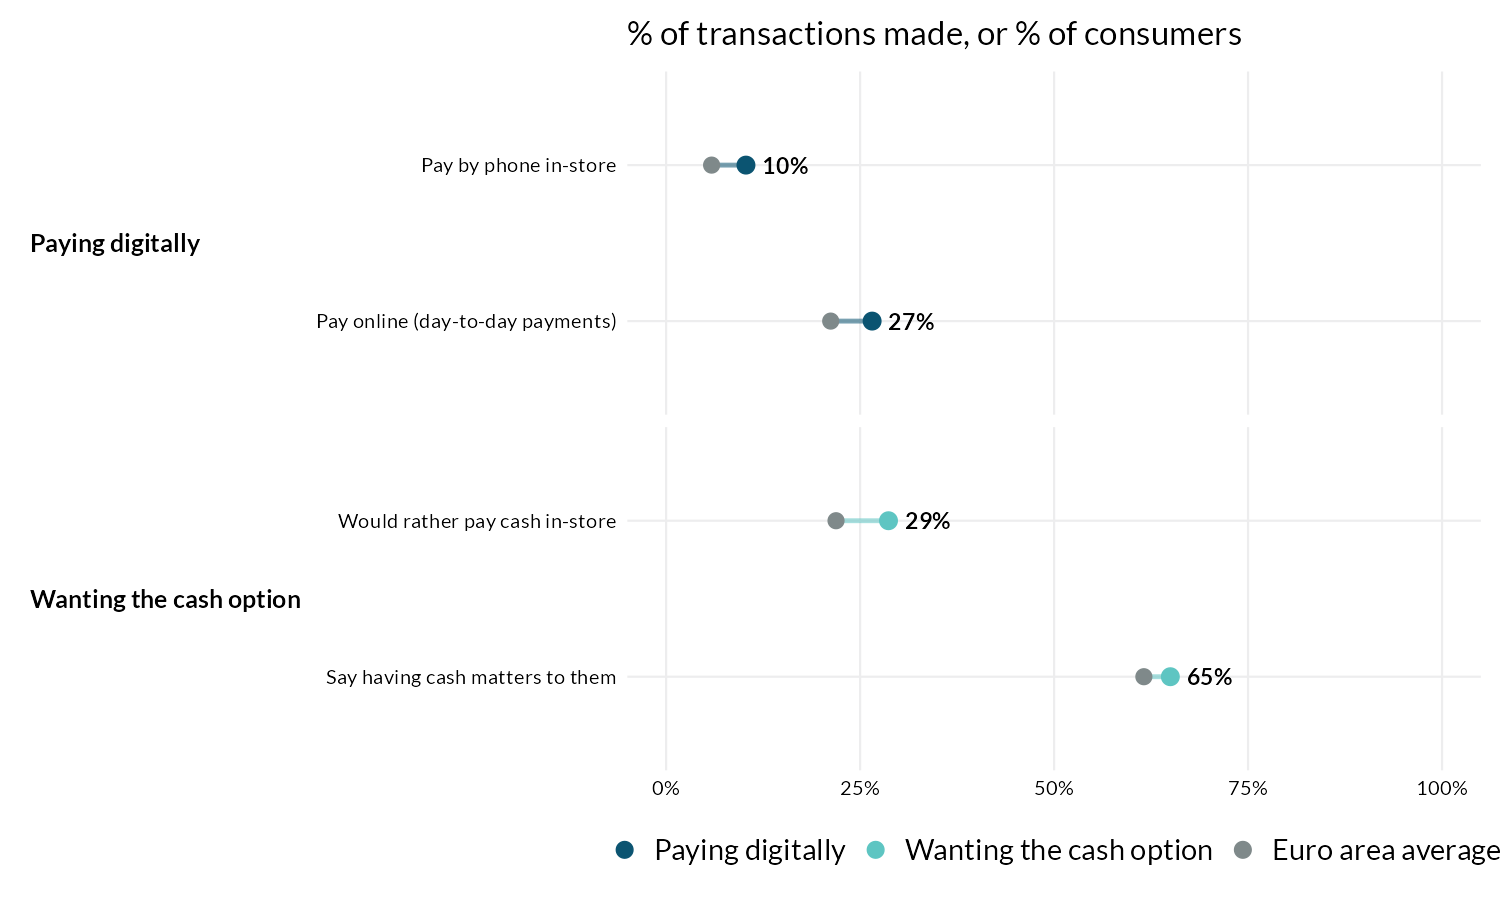
Withdrawing cash less often does not mean that households do not want the option to use cash. In the SPACE survey, 65% of Irish consumers said that having the option to pay in cash was important to them, against 62% across the euro area. Furthermore, 29% said they would rather pay in cash in-store, against 22% in the euro area. Card data show how much cash people take out, but not how much they value having the choice.
Online expenditures are catching up with in-store spending
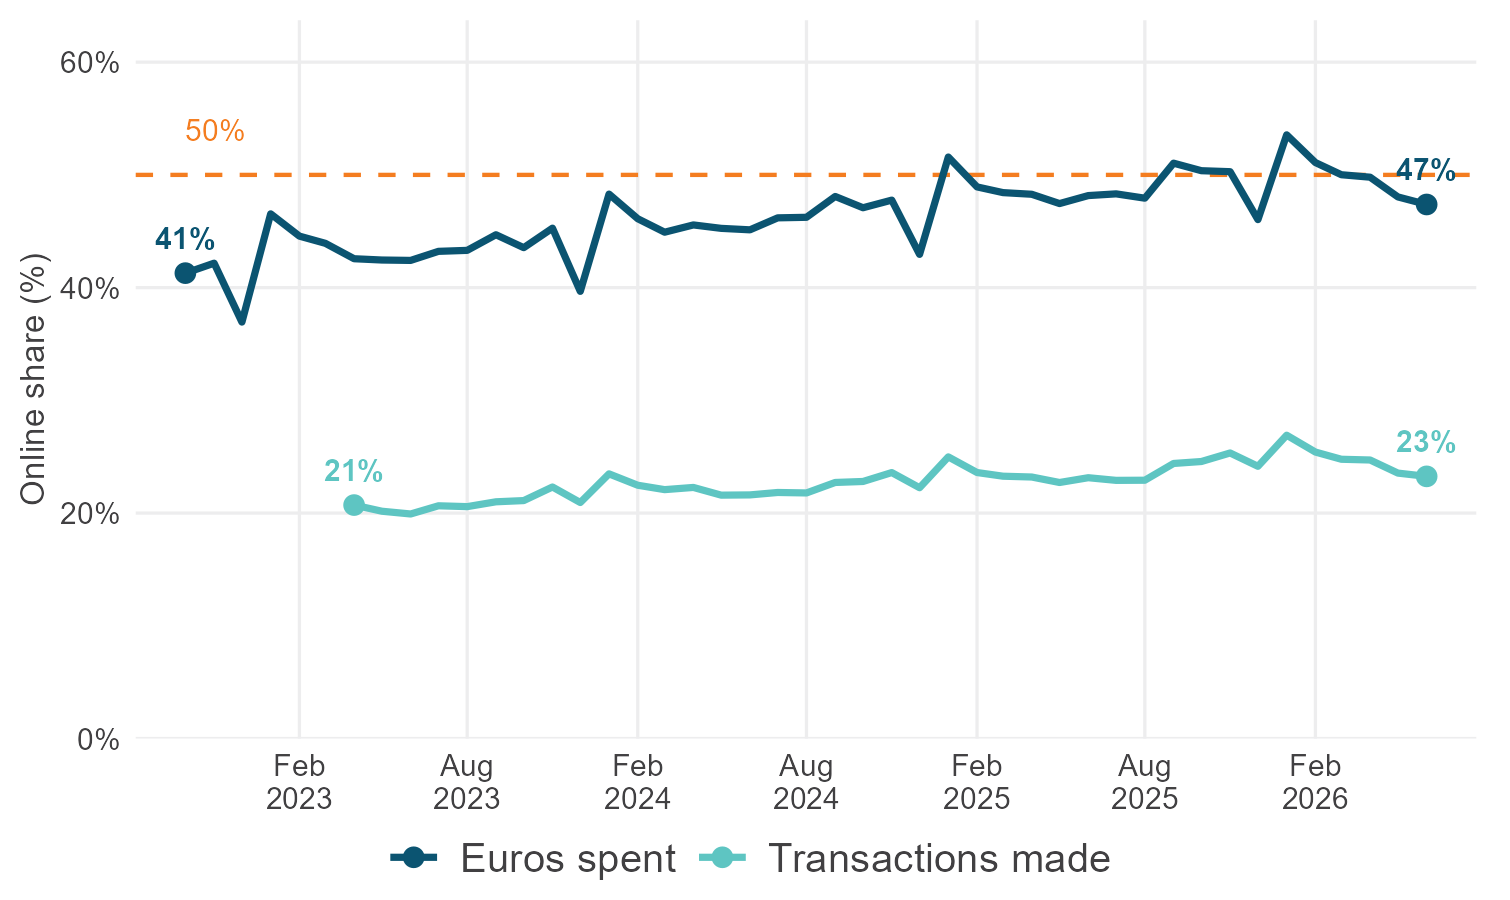
Online spending (by value) has almost closed the gap with in-store spending. Online expenditures were 41.3% of what Irish households spent on their cards domestically in October 2022 and 47.4% in June 2026. Online spending first passed 50% in January 2025 and has averaged 49.5% over the past year (Chart 2).
Focusing on the number of transactions rather than value, spending at in-store point-of-sale (POS) terminals still handles three out of four cards. Online spending accounts for 23% of card volume, up from 21% two years ago. This contrast with value above is explained by in-store spending consisting of a larger number of lower-value payments – the average online payment was €77 in June 2026 against €26 in-store.
Chart 2: Online card spending is close to half the value of in-store spending but under a quarter of the volume
Source: Central Bank of Ireland, Monthly Card Payment Statistics.
Notes: Online payments as a share of domestic card value/volume, which is online and in-store payments. Cash withdrawals are excluded.
Ireland’s use of online card payments is greater than that of the euro area. The SPACE survey found that 21% of everyday transactions across the euro area were made online in 2024, against 27% in Ireland – close to what the card data show.
In the physical world, the phone is replacing the card
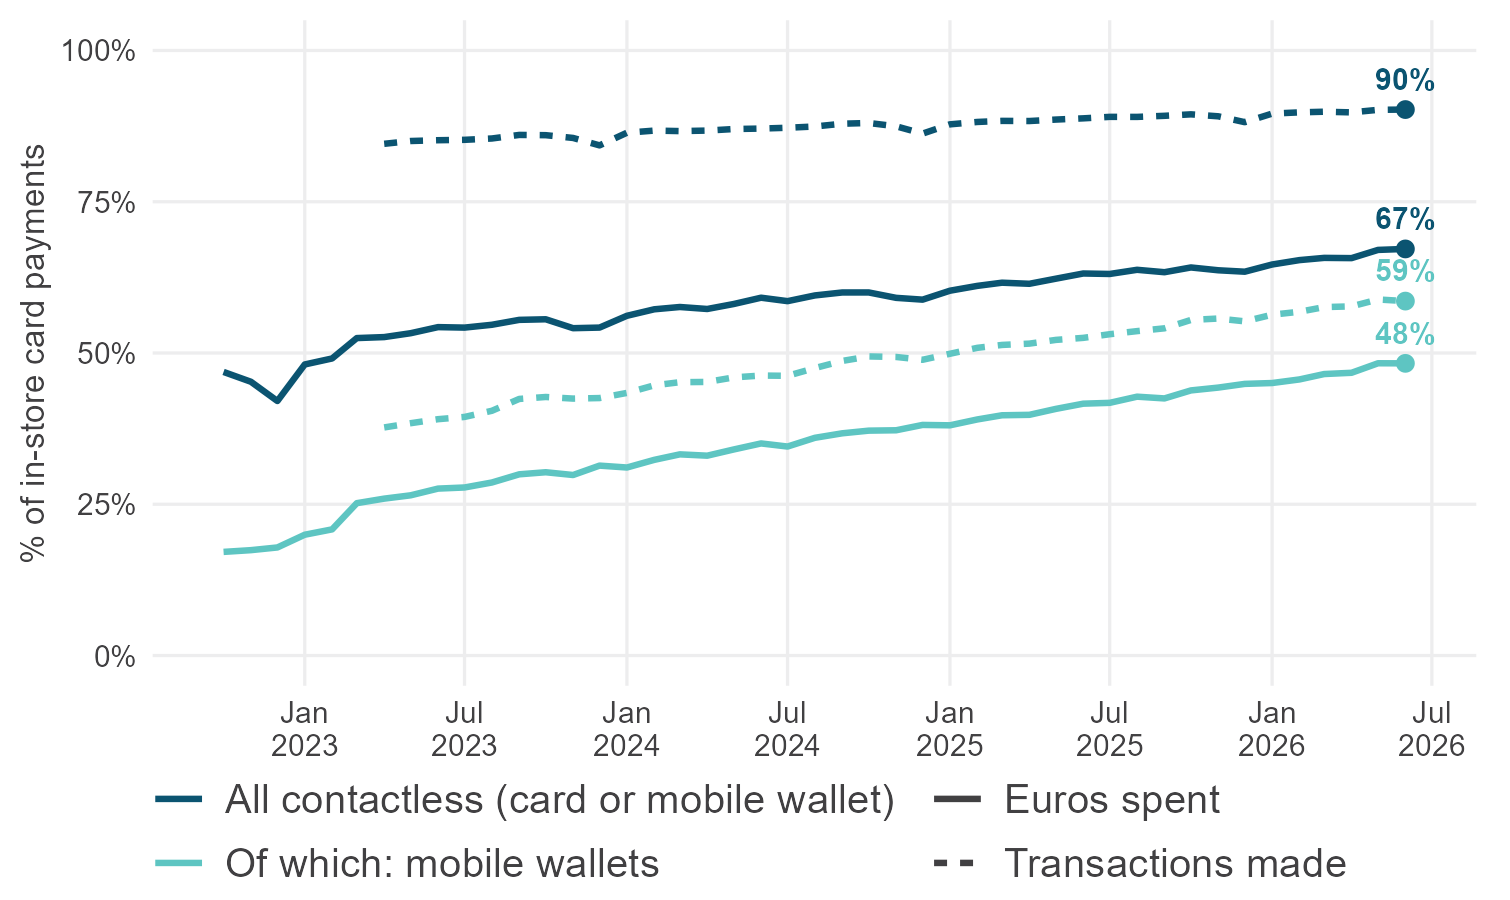
In-store, people have changed what they hold up to the POS terminal. Measured in euros, contactless expenditures rose from 46.9% of in-store card spending in October 2022 to 67.2% in June 2026, and mobile wallet spending from 17.1% to 48.3% (Chart 3). All the growth in the value of contactless payments has come from mobile wallets, as contactless card payments have gone backwards, from 29.7% to 18.9% of all domestic POS value.1
In terms of number of in-store transactions, contactless payments now dominate other card payment methods. Nine in ten transactions were contactless in June 2026, up from 85% in early 2023. Mobile wallets accounted for 59% of in-store card volume, up from 38%. Chip and PIN is now primarily used for occasional large purchases.
Chart 3: At POS terminals, nine in ten transactions are now contactless
Source: Central Bank of Ireland, Monthly Card Payment Statistics.
Notes: Contactless payments and mobile wallets as a share of domestic POS value/volume. Mobile wallet payments are a subset of contactless, so the light blue lines sit below the dark blue ones.
The average value of a mobile wallet payment is growing. Between March 2023 and June 2026, the average contactless card expenditure rose by 3%, from €14.88 to €15.39, while the average mobile phone payment rose 20%, from €17.66 to €21.23. Mobile wallets now make up 65% of contactless volume and 72% of contactless value. European rules let a store take a contactless card payment of up to €50 without asking for a PIN, and most banks treat that as the ceiling for a contactless card payment. A phone checks a fingerprint or a face instead, so it has no ceiling.
That ceiling applies across the European Union, so it cannot explain why Ireland uses mobile payments more than its neighbours. The SPACE survey found that payments by phone passed 10% of in-store transactions in only three countries: the Netherlands, Finland and Ireland, against a euro area average of 6%. Among Irish consumers who prefer not to pay in cash, 23% would rather use a phone than a card, against 14% across the euro area.
Ireland is above the euro area average on both measures of paying digitally and places greater value on wanting the option to pay in cash than the euro area average (Chart 4). These are not contradictions, as a country can adopt new ways to pay quickly and still want cash to remain available.
Chart 4: Irish consumers make more digital payments, but value the option to pay in cash more than the euro area
Source: European Central Bank, Study on the payment attitudes of consumers in the euro area (SPACE) 2024.
Notes: Survey of 50,000 euro area consumers, carried out between September 2023 and June 2024. The first two rows are shares of transactions and the last two are shares of consumers.
Trends differ across counties
The data on payments by county come with two limitations. First, a cash withdrawal or card payment is recorded where the ATM or POS terminal is located, not where the person conducting the transaction lives. Second, the county tables do not report online spending. County-level information is available for cash withdrawals, contactless, and mobile wallet payments. We focus on variations in cash withdrawals and mobile wallet adoption across counties as they represent two opposite ends of the digital adoption spectrum.
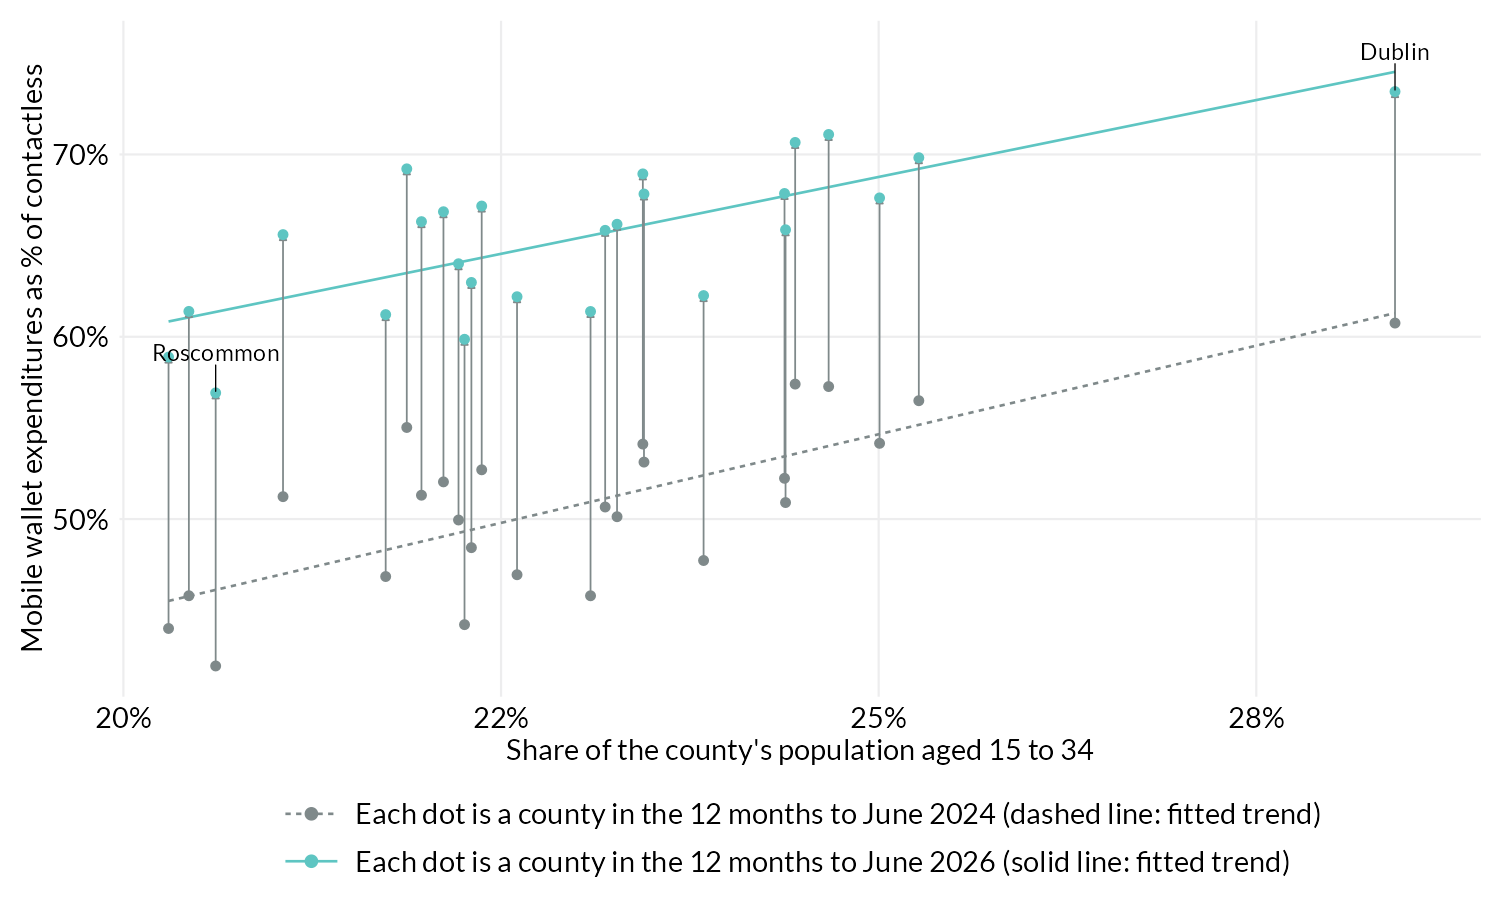
In the twelve months to June 2026, the mobile wallet share of contactless spending ranged from 56.9% in Roscommon to 73.4% in Dublin. To understand what might explain this variation we can look at correlations of mobile wallet adoption (i.e. its share of contactless spending) with characteristics of counties. Correlation measures whether two data series move together or move in opposite directions, and the strength of the relationship between them. A correlation of +1 would mean the two move together perfectly in the same direction, -1 would mean the two move together perfectly in opposite direction and 0 would mean no relationship at all. The correlation for the mobile wallet adoption with the share of residents aged 15 to 34 is +0.73. The mobile wallet share is also higher where incomes are higher (correlation of +0.71) and where more homes have broadband internet (correlation of +0.57).
Differences across counties are relatively persistent (Chart 5). Each vertical line represents a specific county’s mobile wallet adoption from 2024 to 2026. The diagonal lines show a relationship between the share of young residents in a county and rate of digital adoption. Counties with a younger population were ahead in digital adoption two years ago and remain ahead by much the same margin today. Every county gained between 12.7 and 16.0 percentage points in mobile wallet adoption, and the gap between highest and lowest narrowed only slightly, from 18.8 points to 16.5.
Chart 5: Younger counties pay by phone more, and that has not changed
Source: Central Bank of Ireland, Monthly Card Payment Statistics, CSO Census 2022.
Notes: Mobile wallet expenditures as a percent of contactless value. Each arrow is a county, running from the twelve months to June 2024 to the twelve months to June 2026. The dashed line is fitted to the earlier year, the solid to the latter.
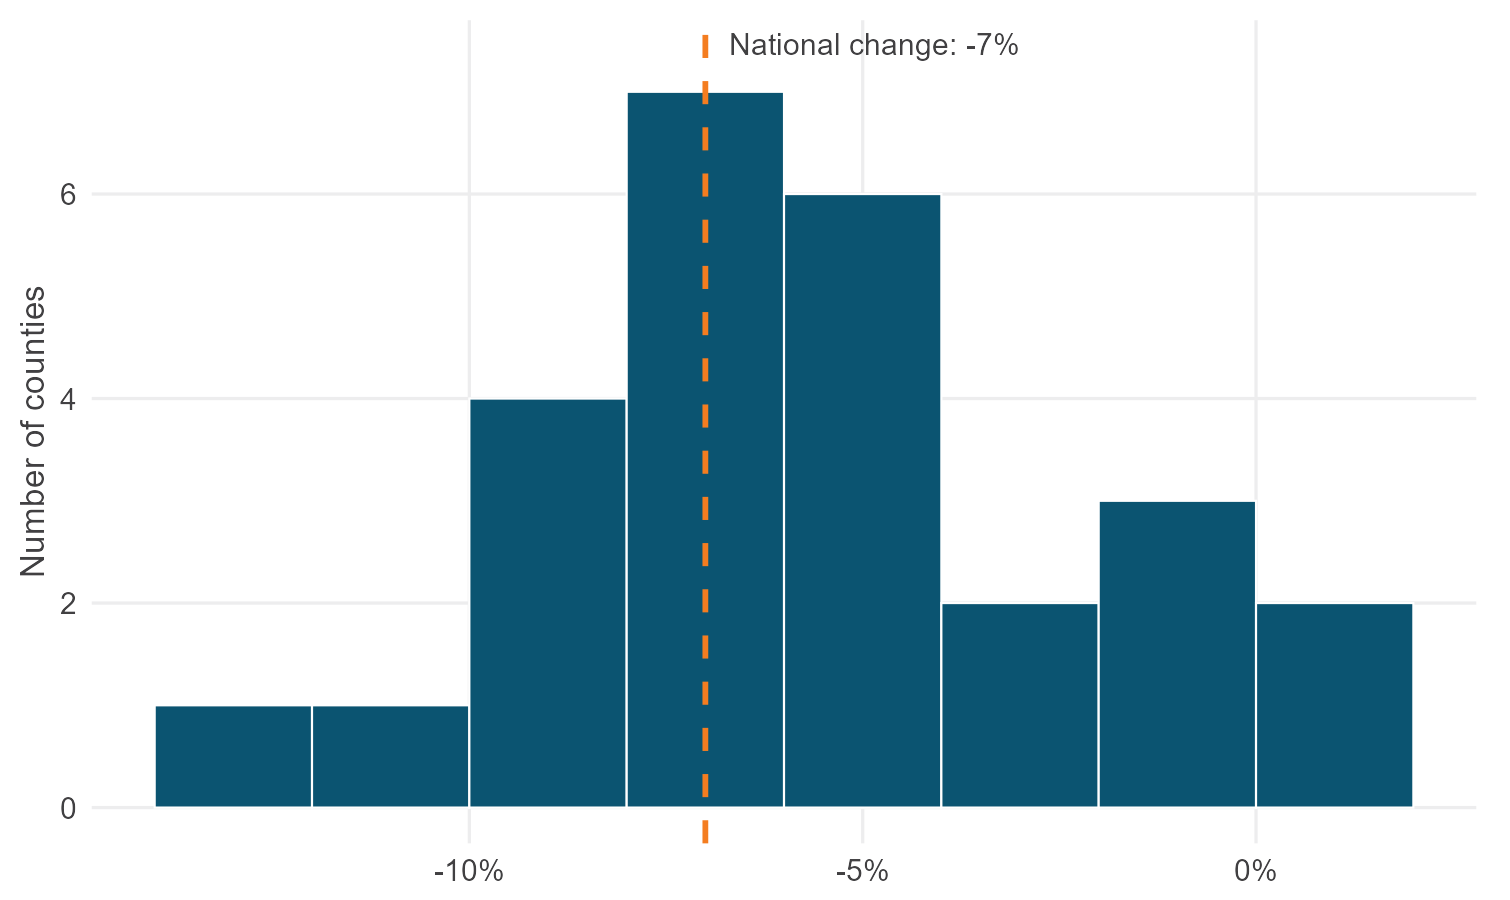
The average cash withdrawal measured on a per resident basis is falling in value, but with greater variation across counties. Nationally, cash taken out per resident fell from about €209 a month to about €194, a drop of 7%, but that average masks county trends. Withdrawals per resident declined 12.6% in Kilkenny and rose in Donegal and Leitrim. Twenty-four of the twenty-six counties recorded a fall in the last two years (see Chart 6).
In relation to explaining why cash withdrawals are falling at different speeds across counties, the correlations are not as strong as for digital adoption. The percentage change in cash withdrawn per resident is negatively correlated with disposable income (−0.42) and positively correlated with the unemployment rate (+0.36). Put simply, cash withdrawal per resident tends to fall more in higher-income counties and less in counties with higher unemployment rates. However, these relationships are modest and do not prove that income or unemployment caused the differences.
Chart 6: Distribution of county-level changes in the value of cash withdrawals per resident
Source: Central Bank of Ireland, Monthly Card Payment Statistics.
Notes: Relative change in the value of cash withdrawals per resident between the twelve months to June 2024 and to June 2026. Cash withdrawals combine ATM withdrawals and cashbacks obtained via card-based transactions.
Conclusion
Ireland’s payment landscape is becoming increasingly digital. Online spending now accounts for close to half of domestic card expenditures, contactless payments dominate at the POS terminals, and mobile wallets are increasingly replacing physical cards. At the same time, people are withdrawing cash less often and cash withdrawals account for a smaller share of the value of all card-based transactions. Taken together, these changes point to a broader shift in how Irish households pay, rather than a change confined to any single payment channel.
However, this change is not simply a move from cash to digital payments. Irish consumers make greater use of digital technology than the euro area average while still placing high value on retaining the option to pay in cash. The county results show why national averages need to be interpreted carefully. Mobile wallet adoption has risen at a similar speed across the country, but cash withdrawals have fallen much more unevenly. Ireland is becoming more digital, but not everywhere and not across every payment channel at the same pace.
*Email patrik.gorse@centralbank.ie if you have any comments or questions on this article. Comments from Barra McCarthy, Patrick Hughes, Vasileios Madouros, Alan Briscoe, Dermot Finneran, Roisin Flaherty, Ciara Doyle, Fergal McCann, David Duignan, and Sangamithra Varadarajan are gratefully acknowledged. The views expressed in this note are those of the author and do not necessarily reflect the views of the Central Bank of Ireland or the ESCB.
[1] While mobile wallets are a subset of contactless payments – a category that also includes contactless physical cards – most mobile wallets are typically linked to an underlying debit or credit card. Therefore, the shift from physical card payments to mobile wallets represents a change in the authorization method rather than a move away from the card networks themselves.